Commercial Solar Finance: Cash vs Loan vs PPA vs Lease
There are four ways a UK business funds rooftop solar: buy it outright, borrow to buy it, sign a power purchase agreement where a funder owns the kit and sells you its output cheaply, or lease. Cash delivers the best lifetime return. A 49.68kWp commercial system with battery storage that we quoted at £37,000 plus VAT showed a payback of circa 4 years and would generate for decades after. Borrowing preserves working capital while keeping ownership and the tax reliefs, and PPAs trade most of the upside for zero capital outlay. The right route is a cashflow decision more than a solar one, which is why we quote the system and let your accountant pick the wrapper. We do not offer or arrange finance, and we take card payments, with a 1.9% fee if you choose to pay that way.
In This Guide
Route 1: cash purchase, the benchmark
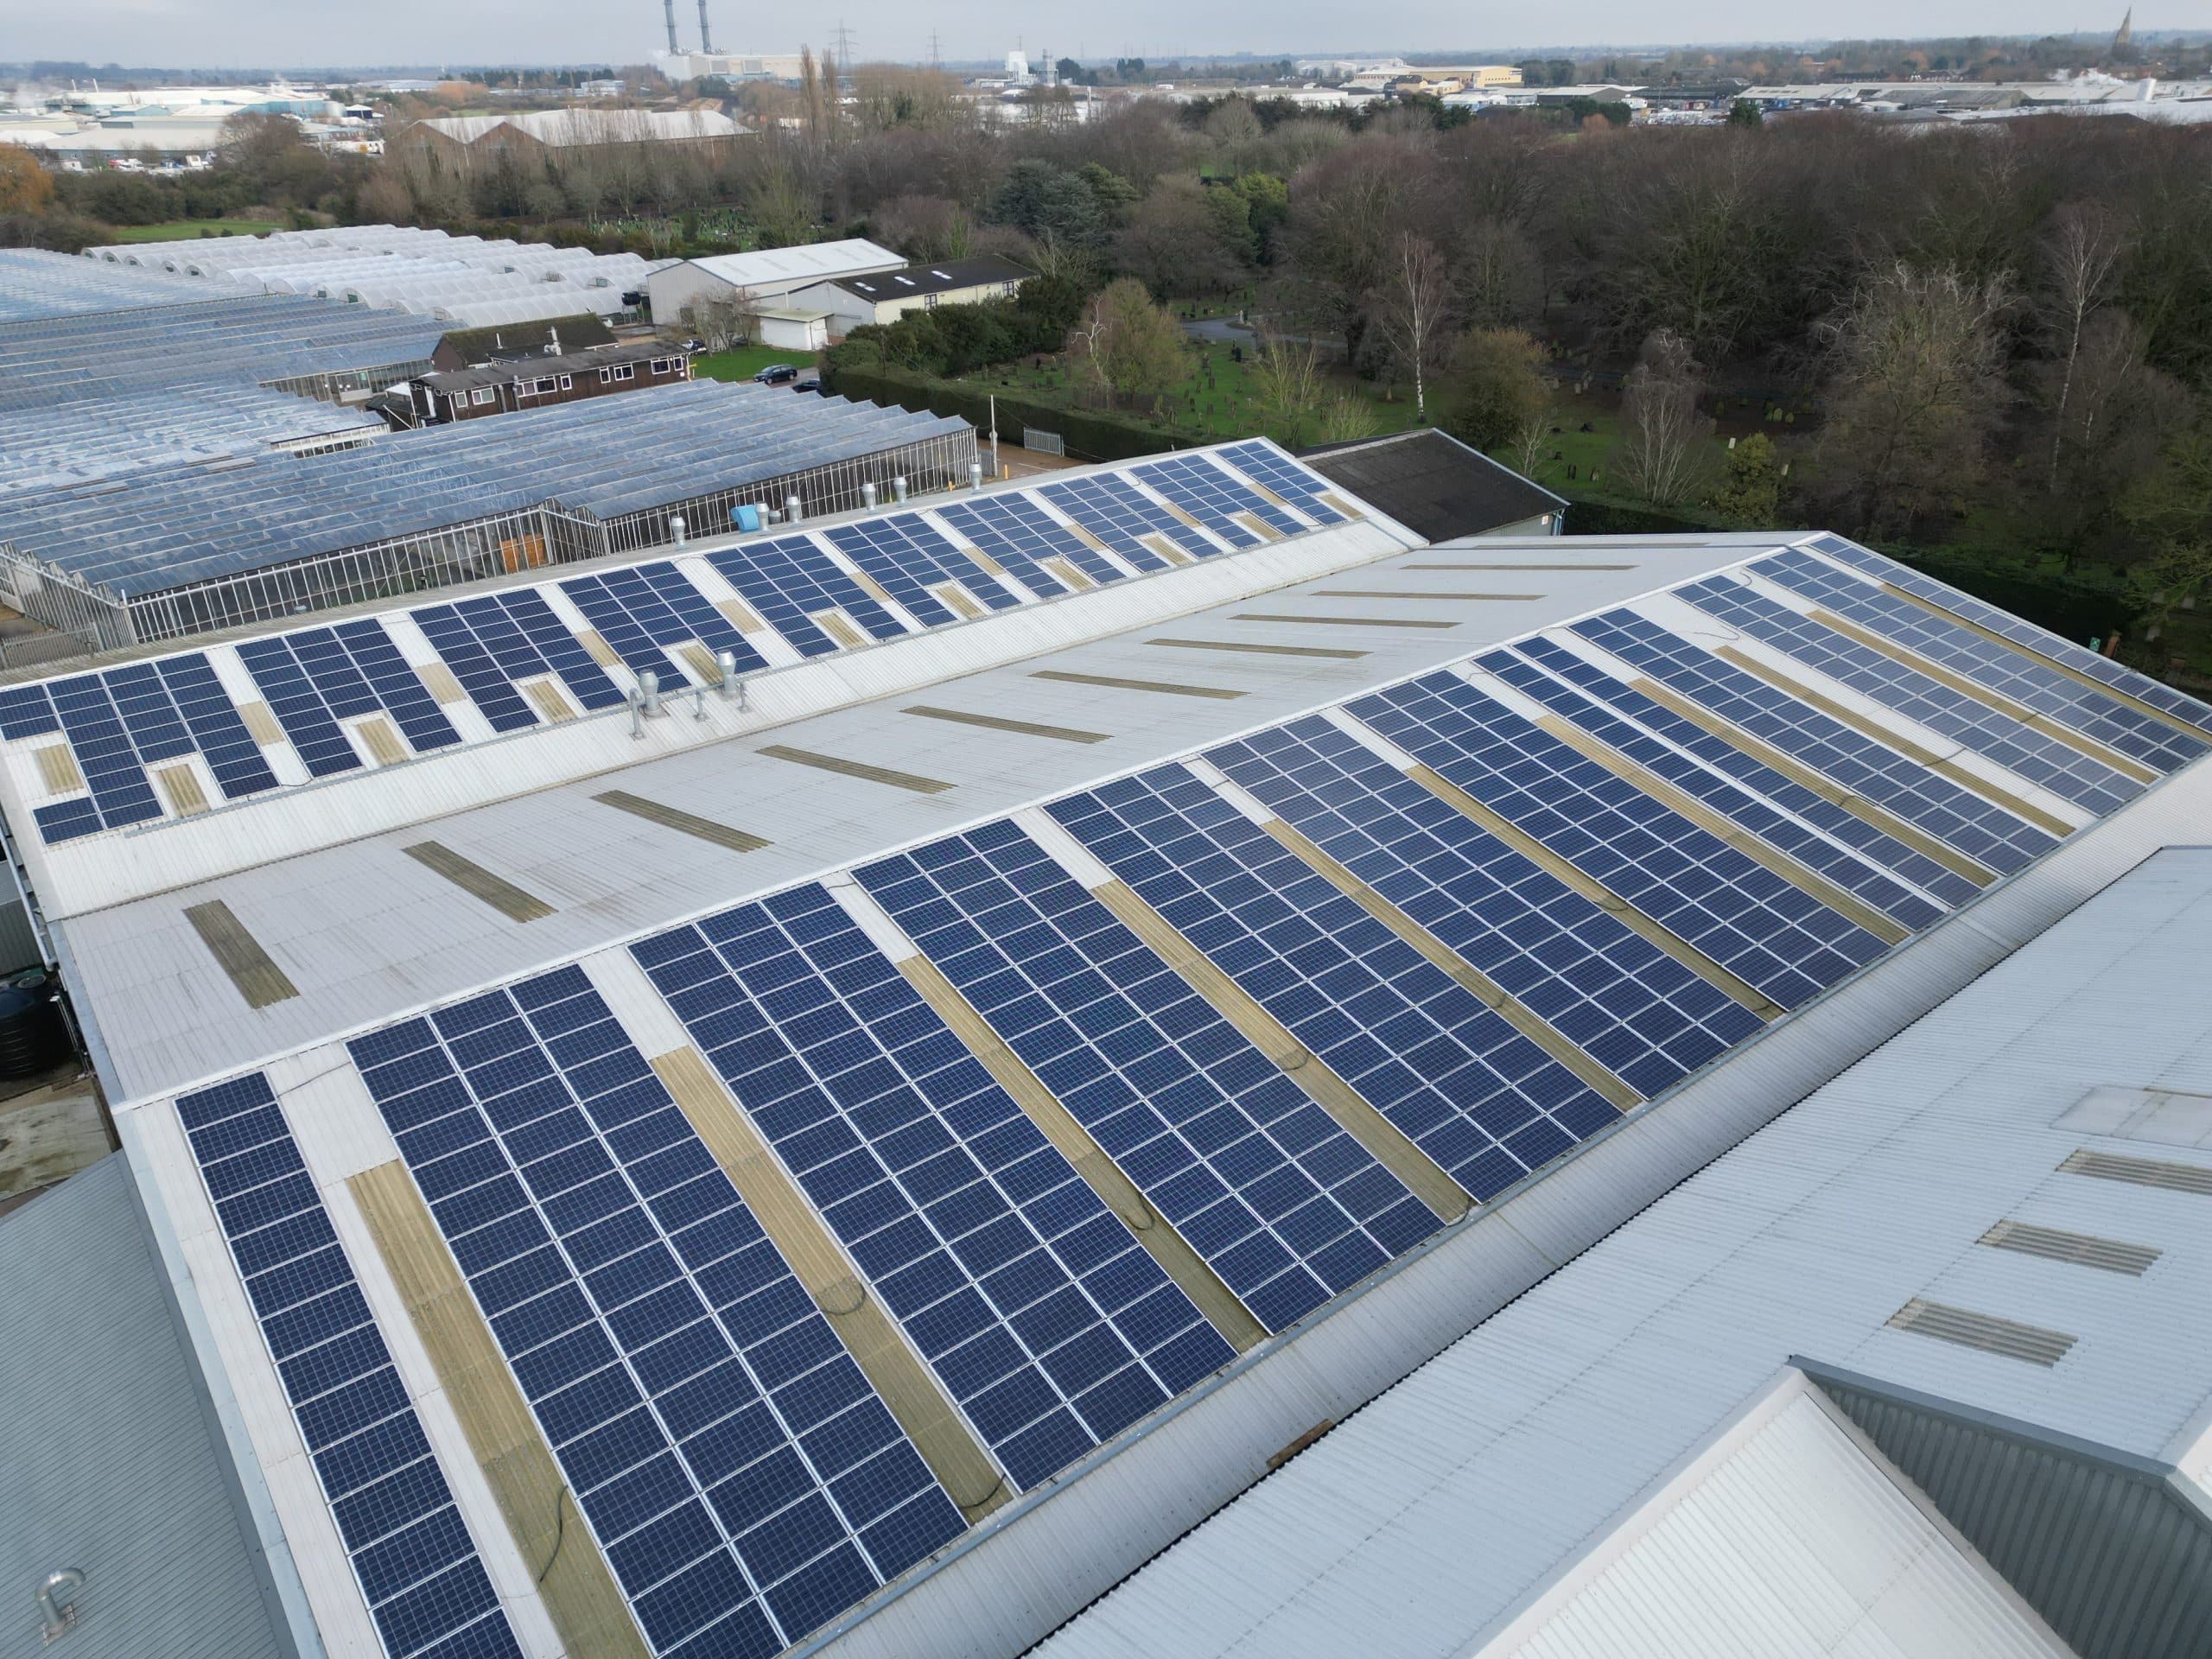
Buying outright is the yardstick every other route gets measured against, because it keeps everything: all the bill savings, all the export income, the capital allowances that let the investment be set against taxable profits, and an asset with a 25-plus-year life on your roof. Our standing example is a real quote: a 49.68kWp system with battery storage at £37,000 plus VAT for a business whose daytime consumption soaks up the generation, which showed a payback of circa 4 years on the arithmetic our commercial payback guide lays out in full. After payback, the system is simply a cost-of-electricity advantage your competitors do not have. The one argument against cash is the honest one: the same capital might earn more deployed in your own trade, which is precisely the case for route two.
Route 2: asset finance, ownership without the capital hit
Borrowing to buy, through a bank loan or asset finance secured on the equipment, keeps the ownership benefits while spreading the cost. Whether the savings would cover the repayments depends on the terms you arrange yourself and on how much of the generation your business uses. You still own the asset, still claim the allowances, still keep every kilowatt-hour of upside, and when the loan ends the savings run on for decades. Whether borrowing suits your business is a question for your accountant, and any borrowing is arranged by you, not through us.
Route 3: the PPA, solar without spending
Under a power purchase agreement, a funder installs and owns the system on your roof, and you commit to buying its output at a rate below your grid price for a long contract, commonly 15 to 25 years. Nothing leaves your capital budget, maintenance is the funder's problem, and your electricity gets cheaper on day one. The trade-offs are equally real: the funder keeps most of the lifetime value, the contract needs legal attention (what happens on sale of the building, on roof repairs, at term end), and PPAs favour bigger roofs and strong covenants, funders want scale and creditworthiness before they deploy capital. It is the right answer for capital-constrained businesses with large roofs and long horizons, and a poor one for a business that could fund the system itself. The contract mechanics deserve their own article, and our PPA guide goes deep on them.
Route 4: leases, the middle path
Equipment leases sit between loan and PPA: a funder owns the system, you pay a fixed rental and keep the generation. Against a loan, the appeal is off-balance-sheet treatment in some structures and predictable payments; against a PPA, you keep the output rather than buying it back. The details matter more than the label, whether maintenance is included, what happens at term end, whether there is a purchase option, and lease accounting rules have tightened, so this is genuinely your accountant's call. Where leases most often make sense: businesses that want fixed costs and no ownership admin but whose roof or covenant does not attract PPA funders.
The four routes side by side
| Route | Capital outlay | Who keeps the upside | Best suited to |
|---|---|---|---|
| Cash | Full | You, entirely | Businesses with reserves and no better use for them |
| Loan / asset finance | None to modest | You, minus interest | Profitable firms preserving working capital. |
| PPA | None | Mostly the funder; you get cheaper power | Large roofs, strong covenants, capital committed elsewhere |
| Lease | None | You keep generation, pay fixed rental | Fixed-cost preference without PPA scale |
Whichever wrapper wins, the engineering underneath is identical, and it is the engineering that decides whether any of the routes pays: a properly sized system matched to your daytime load, on a sound roof, with the G99 grid approval handled early. We design and price the system with the real numbers, including generation modelling and consumption matching, and give you one clear written quote to take to your own advisers.
Get the numbers your accountant needs
A design of your roof, generation modelling and one all-in price your advisers can work from, with a free site survey once you go ahead. Call 0115 773 7575, 8am to 8pm, Monday to Friday.
Get EstimateFrequently asked questions
How do businesses finance commercial solar?
Four routes: cash purchase, loan or asset finance, power purchase agreements where a funder owns the kit and sells you its output, and equipment leases. Cash keeps the most value, finance preserves working capital while keeping ownership, and PPAs remove capital outlay in exchange for most of the upside.
Do you offer finance for commercial solar?
No. We do not offer or arrange finance. We give you one clear written quote that you and your advisers can work from, and we take card payments, with a 1.9% fee if you choose to pay that way.
What is a solar PPA?
A power purchase agreement: a funder installs and owns solar on your roof, and you buy its output at below-grid rates for a long contract, typically 15 to 25 years. Zero capital outlay and maintenance included, in exchange for the funder keeping most of the lifetime value. Our dedicated PPA guide covers the contract detail.
Do businesses get tax relief on solar panels?
Purchased systems can qualify for capital allowances, which let the investment be set against taxable profits and can improve the cash and loan routes. The mechanics and current schemes are covered in our capital allowances guide, and the fine print belongs with your accountant.
Which finance route is best?
It is a cashflow and tax question more than a solar one: cash for businesses with idle reserves, finance for those preserving working capital, PPAs for large roofs with capital committed elsewhere. Get the system designed and priced first, the engineering is identical under every wrapper, then let your advisers choose the structure.
Related reading
- Commercial solar payback: real numbers
- Solar PPAs explained for UK businesses
- Solar and capital allowances
- Solar panels for warehouses
- Domestic solar finance options
Commercial solar since 2011
We are Spectrum Energy Systems, MCS certified (NIC200223), designing and installing commercial solar across the East Midlands, with 10 MW of clean generation connected and one clear written quote your advisers can work from. Call 0115 773 7575, 8am to 8pm, Monday to Friday.
Get in touch